Market overview and structural scope of the Aerosol Can Market
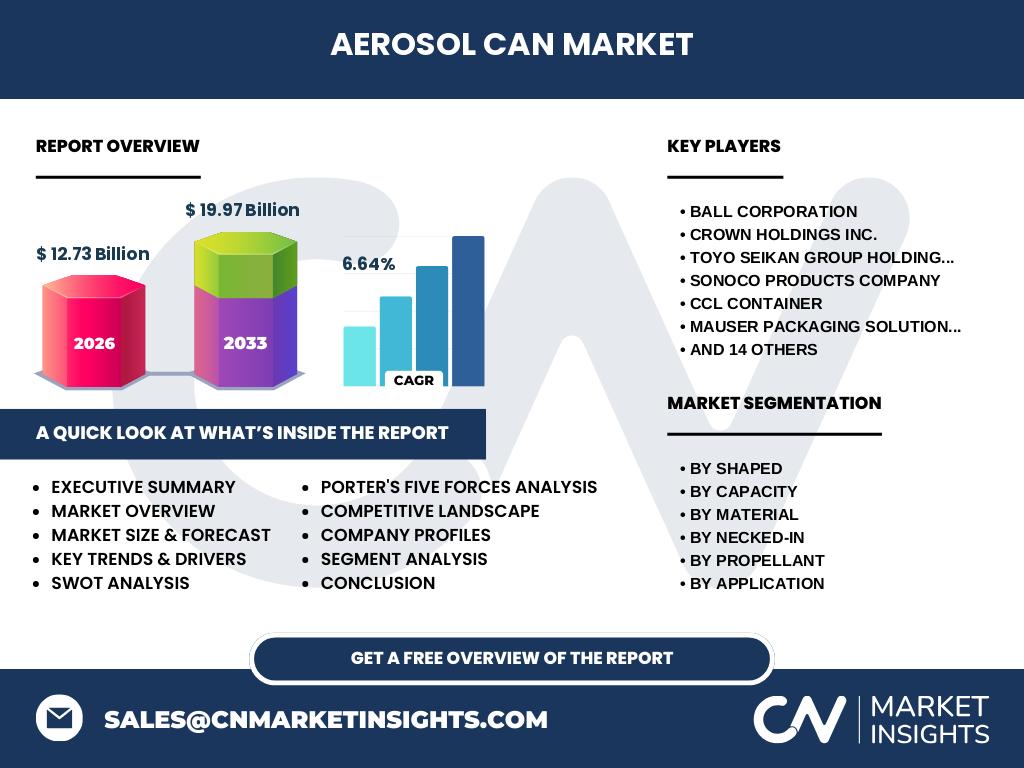
Our analysis indicates that the Aerosol Can Market encompasses the production, distribution, and material processing of pressurized containers utilized globally. Reaching a baseline valuation of 12.73 Billion in 2026, the sector underpins high-speed packaging lines for personal care, household, and pharmaceutical goods, relying heavily on precision extrusion and metal forming technologies.
What are the primary market drivers, restraints, and opportunities shaping the Aerosol Can Market?
Growth is propelled by surging demand for sustainable metal packaging, though constrained by stringent volatile organic compound regulations enforced by bodies like the EPA. Substantial opportunities lie in adopting lightweight aluminum alloys and expanding Bag-On-Valve technology to meet pharmaceutical purity demands.
Emerging trends and growth patterns in the Aerosol Can Market
The data highlights an aggressive pivot toward customized and shaped containers, particularly Slim Shaped and Hourglass Shaped units. Industry leaders are leveraging advanced necking-in processes to reduce metal usage while enhancing ergonomic appeal and shelf differentiation for premium cosmetic brands.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain bottlenecks for critical raw materials like primary aluminum and steel coil. However, accelerated post-pandemic demand for surface disinfectants and pharmaceutical sprays drove a robust market rebound, setting the stage for sustained expansion toward our 19.97 Billion forecast.
Competitive landscape and strategic market concentration
Market concentration remains moderately high, anchored by tier-one multinational giants such as Ball Corporation, Crown Holdings Inc., and Trivium Packaging. These heavyweights focus on proprietary alloy developments and localized manufacturing footprints to mitigate cross-border freight volatility and secure long-term supply agreements.
Executive summary of key findings in the Aerosol Can Market
Our exhaustive research projects the Aerosol Can Market to expand at a steady 6.64% CAGR from 2027 to 2033. Strategic investments in infinite-recyclable aluminum substrates and specialized propellant formulations will dictate market leadership as sustainability mandates tighten globally.
Market forecast trajectory from 2027 to 2033
Driven by robust demand across automotive and personal care applications, the market valuation is set to scale from its 2026 baseline to 19.97 Billion by 2033. This expansion reflects a compounded annual growth rate of 6.64%, heavily supported by emerging manufacturing hubs in developing economies.
Segmentation analysis across material, capacity, and application
The market segments by material (aluminum, steel, plastic), capacity (ranging from under 100ml to over 500ml), and product type including Straight Wall and Necked-In variants. Aluminum dominates premium segments due to its corrosion resistance and infinitely recyclable properties, whereas steel serves heavy-duty industrial and automotive aerosol needs.
Regional market analysis and geographic performance
Geographic distribution exhibits strong manufacturing concentrations in North America and Europe, supported by strict regional safety standards enforced by organizations like the FEA. Meanwhile, Asia-Pacific represents the fastest-growing frontier, fueled by expanding urban middle-class demographics and rising disposable incomes.
In-depth regional review of manufacturing hubs and consumption
Asia-Pacific consumption is heavily anchored by localized production facilities operated by players like Toyo Seikan Group Holdings Ltd. and CPMC Holdings Limited. Western markets prioritize eco-design regulations, forcing converters to scale up post-consumer recycled aluminum integration to maintain market share.
Company profiles and strategic positioning of leading innovators
Key market participants deploy distinct growth strategies; Sonoco Products Company and Mauser Packaging Solutions focus on diversified rigid packaging portfolios, while specialized players like CCL Container excel in seamless impact-extruded aluminum containers tailored for high-end personal care brands.
Porter's Five Forces analysis of competitive intensity
Bargaining power of suppliers is high due to primary aluminum pricing volatility, while threat of substitutes is mitigated by the unmatched barrier properties of pressurized metal cans. Competitive rivalry remains intense, pressing firms to innovate continuously in propellant efficiency and container weight reduction.
SWOT analysis highlighting strategic inflection points
Core strengths include excellent shelf life and barrier protection. Weaknesses involve high energy consumption during metal smelting. Opportunities exist in eco-friendly propellant conversions, while threats center on rising raw material tariffs and alternative packaging formats like trigger sprays.
Value chain analysis from bauxite mining to end-user delivery
The value chain initiates with bauxite mining and aluminum smelting, progressing through coil coating, slug punching, impact extrusion, internal lacquering, and high-speed lithographic printing. Value capture concentrates heavily at the manufacturing and specialized necking-in stages before distribution to brand owners.
Investment insights and high-potential areas for stakeholders
High-potential capital allocation targets automated, high-speed production lines capable of processing ultra-thin aluminum walls and advanced Bag-On-Valve systems. Investors should prioritize asset-light converters partnering directly with global consumer goods giants committed to strict net-zero carbon packaging targets.
Conclusion and key strategic takeaways for industry participants
Navigating the Aerosol Can Market requires balancing aggressive lightweighting initiatives with strict compliance alongside global safety standards. Firms that successfully integrate sustainable post-consumer recycled metals while expanding customized shaped offerings will capture disproportionate profit pools through 2033.
Research methodology for baseline estimation and data triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data from customs authorities, conducting primary stakeholder interviews with packaging engineers and procurement directors, and evaluating secondary macroeconomic indicators such as regional manufacturing PMI indices.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue performance, volume shipments, and material breakdowns across commercial sectors from 2026 to 2033. Limitations include unforeseen geopolitical trade disruptions and sudden regulatory shifts regarding propellant classifications that may alter short-term pricing dynamics.
Recent developments in strategic partnerships, product launches, and mergers
Recent industry momentum features major capital investments by Trivium Packaging and Crown Holdings Inc. into low-carbon aluminum sourcing and solar-powered manufacturing plants. Simultaneously, strategic collaborations between regional fillers and innovators like Colep Packaging aim to commercialize ultra-lightweight propellant delivery systems.